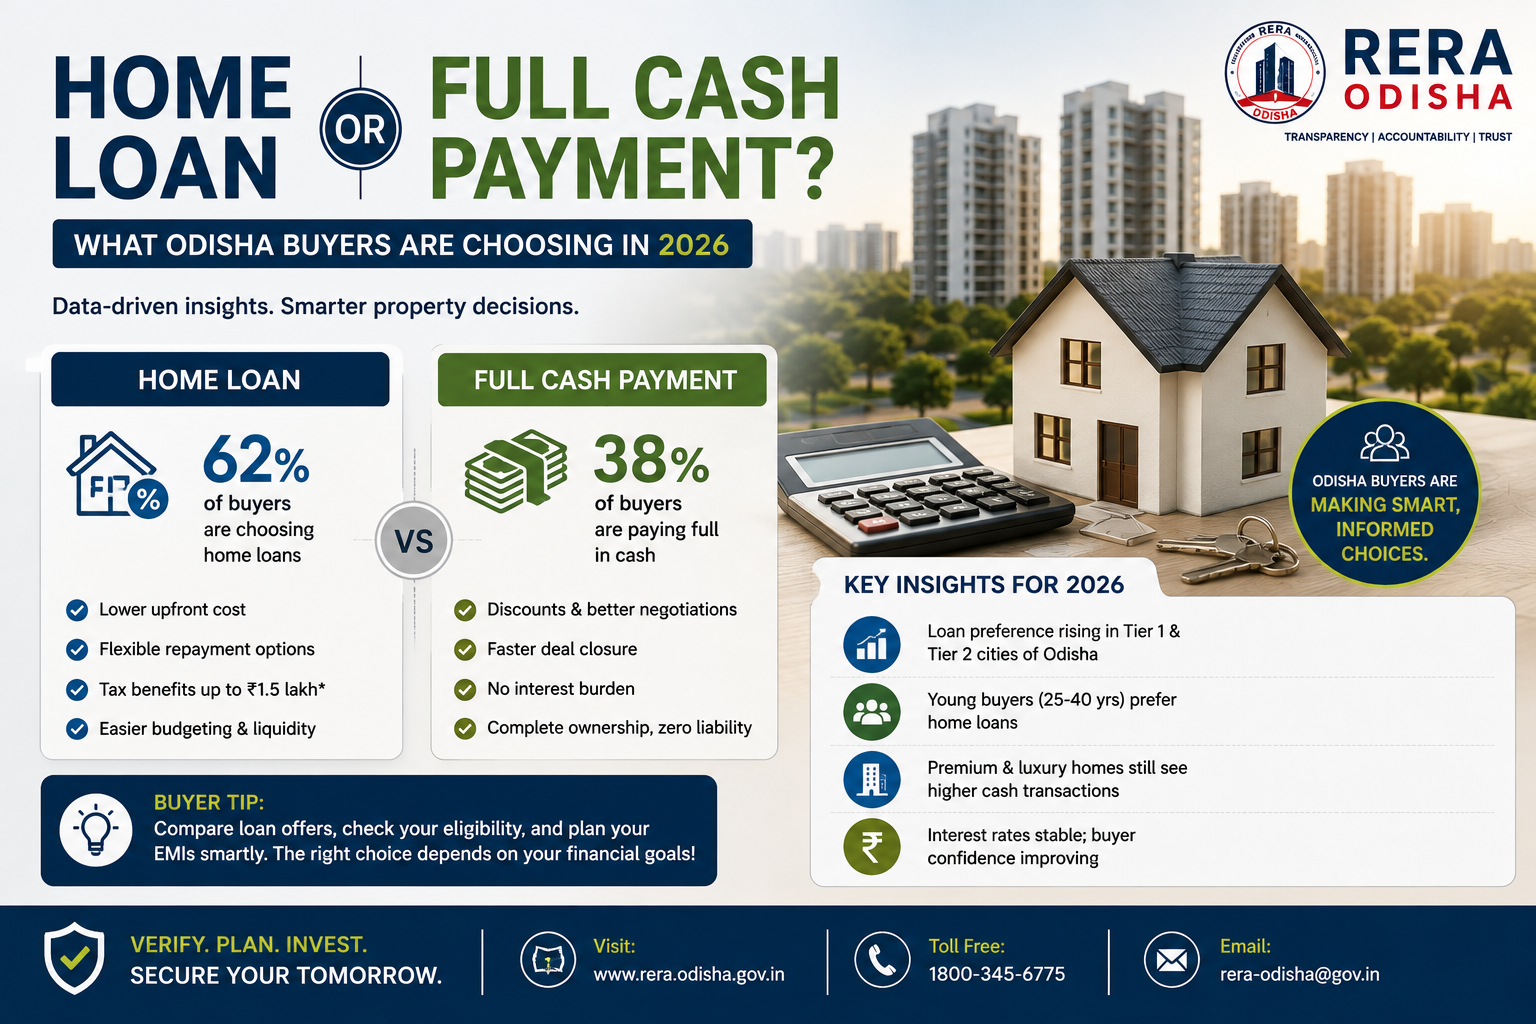
With home loan interest rates holding steady through much of 2026, many first-time buyers in Bhubaneswar and Cuttack are weighing whether to stretch a loan over 15-20 years or make a larger upfront payment to reduce EMI burden.
The case for a home loan
Beyond preserving liquidity, a home loan lets you claim deductions on both principal and interest under the Income Tax Act, which can meaningfully lower your effective cost of borrowing over time — particularly useful for salaried buyers.
The case for paying more upfront
For buyers with surplus savings and low risk appetite, a larger down payment reduces total interest outgo and removes long-term EMI dependency, which matters more as retirement planning enters the picture.
A middle path
Many buyers we work with choose a hybrid: a down payment large enough to secure a meaningfully lower interest slab, paired with a shorter loan tenure. Speak with your bank and a financial advisor before finalising a builder-linked payment plan, since these often carry different terms than a standard loan.